Allocation
This is the only page of the site that talks about a product. The Dollar Double Digits thesis is becoming a single investment: a dollar note, still being structured. Nothing here is an offer.
Being structured
The dollar note: active management, in a single position.
The thesis is becoming a single investment: a dollar note (working name: ETN), actively managed, holding BDCs, fixed-income closed-end funds and mortgage REITs.
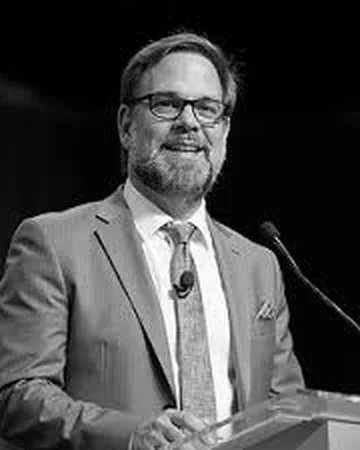 John Cole Scott, CFSPresident and CIO of CEF AdvisorsManager of the note being structured.
CEF Advisors
:Management
Dollar Double Digits
:Design and coordination
Avenue
:Distribution · under discussion
What the proposal sets out
- 20 to 30 holdings in a single position, with at most 7.5% in each and 20% per manager group.
- Active management, with monthly monitoring and a quarterly review of the portfolio.
- 1x exposure: the note adds no leverage to what the assets already use.
- Payments in dollars, at a frequency to be defined.
I want to receive the final factsheet
The risk, in one place
For qualified or professional investors (CVM Resolution 30). You can lose capital and payments can fall. An ETN adds the issuer's credit risk, and the investor does not own the reference assets. The figures on this page are market data for asset classes: they are neither the portfolio nor the yield of the note.
The parameters and the distribution channel are proposals, subject to agreement. Material for discussion; not an offer.
Factsheet of Nov 4, 2026 · discussion draft
- 70%Flexible coreBDCs and fixed-income CEFs
- 30%Mortgage REITsSpecialized analysis
Starting point: 70% BDCs and 30% mortgage REITs. The 70% core may include US-taxable fixed-income CEFs, depending on the mandate to be agreed.
Who does what
CEF Advisors
Management
Manager of the whole portfolio, with an outside specialist in mortgage REITs. CEF Advisors is an SEC-registered investment adviser led by John Cole Scott, CFS, President and CIO, founder of CEFData.com.
Dollar Double Digits
Design and coordination
Product design and coordination of the partners.
Avenue
Distribution · under discussion
Potential distribution channel for Brazilian investors. No agreement has been confirmed yet.
Who the manager is
John Cole Scott, CFS
President and CIO of CEF Advisors
Manager of the note being structured.
LinkedIn (opens in a new tab)CEFData.com (opens in a new tab)
- 1989
CEF Advisors is founded. It is an SEC-registered investment adviser specialised in closed-end funds (CEFs) and BDCs, today based in Richmond, Virginia.
- 2001
John joins the firm, alongside his father, George, after graduating from the College of William & Mary.
- 2008
He founds CEFData.com, a data service that today covers US closed-end funds, BDCs and interval funds, listed and non-listed.
- 2019
He founds the Active Investment Company Alliance (AICA), a non-profit trade association of the closed-end fund industry, and serves as its executive chairman.
- Today
He is President, Chief Investment Officer and Chief Compliance Officer of CEF Advisors. He holds the FINRA Series 66 licence and the Certified Fund Specialist (CFS) designation.
A career history, from public sources of CEF Advisors itself. It is not a performance record.
Sources, read on Nov 14, 2026: CEF Advisors, team page (opens in a new tab); CEF Advisors, Form ADV Part 2 (opens in a new tab); AICA, about the association (opens in a new tab).
Proposed features
- Vehicle
- ETN being structured. This is a working name: the legal form and the listing depend on the final structure.
- Currency
- US dollar (USD)
- Management
- Active
- Exposure
- 1x, with no additional leverage. The underlying assets may use leverage.
- Portfolio
- 20 to 30 holdings; up to 7.5% per holding and 20% per manager group.
- Monitoring
- Monthly and on events
- Review
- Quarterly and on events
- Payments
- In dollars; frequency to be defined
Next steps
- Set the total fee and the taxation
- Choose the issuer, the ISIN and the exchange
- Fix the maturity and the minimum investment
- Close the trading and redemption terms: timing and spreads
Risks
You may lose capital and payments may be reduced. Credit, interest-rate, underlying-leverage, liquidity, CEF-discount, mortgage-financing and USD/BRL currency risks. An ETN adds the issuer's credit risk, and the investor does not own the reference assets. No capital protection should be assumed. Distributions are not total return; the name Dollar Double Digits does not promise a yield.
How do we handle risk? We do not chase the highest yield.
- Paid per year, on its price
- 28.7%
- Total return over 12 months
- -30.1%
It is the same fund, on the same date. A yield far above its peers is read as a warning, not a shortcut.
OXLC, a US closed-end fund of very high risk: distribution rate on price and 12-month total return on net asset value (NAV). Source: CEF Connect (opens in a new tab), Oct 16, 2026. An illustration, not a recommendation.
Market data (source and date shown). Not a promise of returns. Past performance does not guarantee future results.
What the selection looks at before the yield
Total return held up.
NAV per share fell over the year, but NAV total return was +6.3% for CEFData's large-cap BDC index and +3.5% for small-cap.
The market prices quality.
BDCs with ROE of 7% or more trade at a median 30% premium to NAV; negative-ROE names sit at a 35% discount.
Reading of the BDCs' Q3 2026, by John Cole Scott (CEF Advisors Research, November 2026). Index returns do not reflect fees or expenses and are not the performance of CEF Advisors or of the note.
See the reading of the quarterYou can lose capital. Payments can fall and the dollar moves against the real.
In the US, dividends usually have 30% withheld at source: the net figure can be much lower than the gross one. See the sum and its sources
See the second example and the chart
ECC · Eagle Point Credit
- Paid per year, on its price
- 24.8%
- Total return over 12 months
- -25.5%
Source: ECC · CEF Connect (opens in a new tab), Oct 16, 2026
Distribution and return, side by side
- OXLC28.7%-30.1%
- ECC24.8%-25.5%
| Ticker | Distribution rate on price | 12-month total return on NAV |
|---|---|---|
| OXLC | 28.7% | -30.1% |
| ECC | 24.8% | -25.5% |
Who it is for. Who it is not for.
It makes sense for someone who
Is a business owner or a family with wealth outside the company, often after selling it or facing a succession.
Wants part of that wealth earning in dollars and has a horizon of years.
Accepts seeing the price move along the way in order to receive distributions over time.
Wants to understand each asset before deciding: where the income comes from and what risk it carries.
It is not for someone who
Is looking for a promised income or a set deadline.
Will need the money within a few months: some assets have limited liquidity.
Cannot tolerate a fall in price: a high yield comes with a high risk.
Wants a list of assets to buy alone: this page recommends none.
If you see yourself in the first column, the conversation is worth your time.
There is no formal minimum for the conversation. Several assets in this thesis are restricted to qualified (R$ 1 million+) or professional (R$ 10 million+) investors under CVM Resolution 30.
Questions that usually come before the conversation.
Is your question not here? It is a good way to start the conversation. Start the conversation
What is the dollar note?
A single investment in dollars (working name: ETN), actively managed, holding BDCs, fixed-income closed-end funds and mortgage REITs. The proposal sets out 20 to 30 holdings, with at most 7.5% in each and 20% per manager group, and 1x exposure, with no additional leverage.
It is being structured: fee, issuer, maturity, minimum investment and redemption terms are still to be defined. Nothing on this page is an offer.
Who manages the note?
CEF Advisors, an SEC-registered investment adviser founded in 1989 and specialised in closed-end funds and BDCs. John Cole Scott, CFS, its President and CIO, has been with the firm since 2001 and founded CEFData.com, a data service for the industry. An outside specialist handles the analysis of mortgage REITs.
It is a career history, read on the firm's own public pages. It is not a performance record.
How do I receive the income?
Under the proposal, in dollars. The frequency of the payments is still to be defined.
The amount follows what the assets in the portfolio distribute: it is neither fixed nor contracted, and it can fall.
Why not buy the ETFs on my own?
An index ETF holds every company in the index, by its weight, the good ones and the ones under stress. And the distance between them is wide: in CEF Advisors' reading of Q3 2026, BDCs with ROE of 7% or more traded at a median 30% premium to NAV, and negative-ROE names at a 35% discount.
The proposal of the note is to choose: 20 to 30 holdings, a limit per holding and per manager, monthly monitoring. Active management has a cost and does not guarantee a better result than the index.
What does “double digits” mean?
It is the gross yield we aim for across the portfolio: annual distributions of 10% or more on price, before taxes and costs.
It is a construction objective, not a contracted result and not total return: the price of the pieces moves along the way.
When will I be able to invest?
When the note is issued. Today it is being structured: the manager is chosen and the portfolio has a proposal; the fee, issuer, maturity, minimum investment and redemption terms are still open.
Nothing on this page is an offer. Whoever wants to receive the final factsheet and follow the next steps does so through the conversation.
Is there a minimum amount?
For the conversation, there is no formal minimum.
For the thesis, eligibility follows CVM Resolution 30: several assets are restricted to qualified investors (R$ 1 million or more in investments) or professional investors (R$ 10 million or more). It is one of the first things looked at in the diagnosis.
The minimum investment of the note being structured has not been defined yet.
How is Dollar Double Digits paid?
The conversation is not charged for. We are paid through a share of the management fee of the product: the dollar note (ETN/ETP) that is being structured. The total fee of the product is still to be defined.
That means we earn when the product receives investments. It is an interest you should weigh.
Can I lose money?
Yes. Every piece of the thesis carries credit, market and currency risk, and some use leverage.
That is why the selection does not chase the highest yield: it looks first at dividend coverage, book value per share and credit quality. That reduces the risk; it does not remove it.
How much is left after tax?
It depends on the type of income and on the vehicle. In the illustrative sum in the Academy, out of every US$ 100 of gross income US$ 70 is left when 30% is withheld in the US and US$ 85 when it is not, before costs, IOF and currency.
The sum applies to someone who receives the income directly, in an account of their own abroad; the taxation of the note being structured is still to be defined. It is an illustration with the general rates, not tax advice. Check your own case with your accountant.
What if the dollar falls?
The income is still in dollars, but it is worth less in reais. Over 12-month windows between Nov 2016 and Oct 2026, the dollar has fallen 22.0% and has risen 43.5% against the real.
The thesis makes no currency forecast. Anyone who spends in reais takes that swing along with the income, in both directions.
Can I get out whenever I want?
It depends on the piece. ETFs and listed shares trade every day; unlisted private credit has redemption windows and limits; venture is illiquid. The Liquidity column of the table in the Academy shows it piece by piece.
Daily liquidity is not a stable price: you can sell, but at the price of the day.
For the note being structured, the terms and conditions of trading and redemption are still to be defined.
What about inheritance of assets in the United States?
Shares and funds of US companies count as assets situated in the US. Above US$ 60,000, the estate of someone who is neither a US resident nor a US citizen falls under the US estate tax, with a top rate of 40%.
That weighs on the choice of vehicle; for the note being structured it depends on the issuer and the structure, still to be defined. Estate planning stays with your lawyer.
Does this page recommend any investment?
No. The material is informational: it shows market data with source and date, and tickers appear as examples, not as a buy list.
An individual decision goes through the suitability analysis for your profile.
What happens to the data in the form?
They are used only to answer your message and, if you ask, to tell you when the course opens. The page uses no cookies.
How do I start? Investing in dollars starts with a conversation.
No account is opened and nothing is bought here. Tell me in a few lines where you stand: I reply personally within one business day, with no product on the table.
Prefer to talk by message? Chat on WhatsApp (opens in a new tab)